Let’s define how Afterpay and BNPL work for merchants in 2026
Buy now pay later (BNPL) lets a customer split a purchase into installments. In the U.S., Afterpay now appears as Cash App Afterpay, but the merchant checkout and settlement process is generally the same. Other well-known options include Klarna, Affirm and PayPal Pay Later.
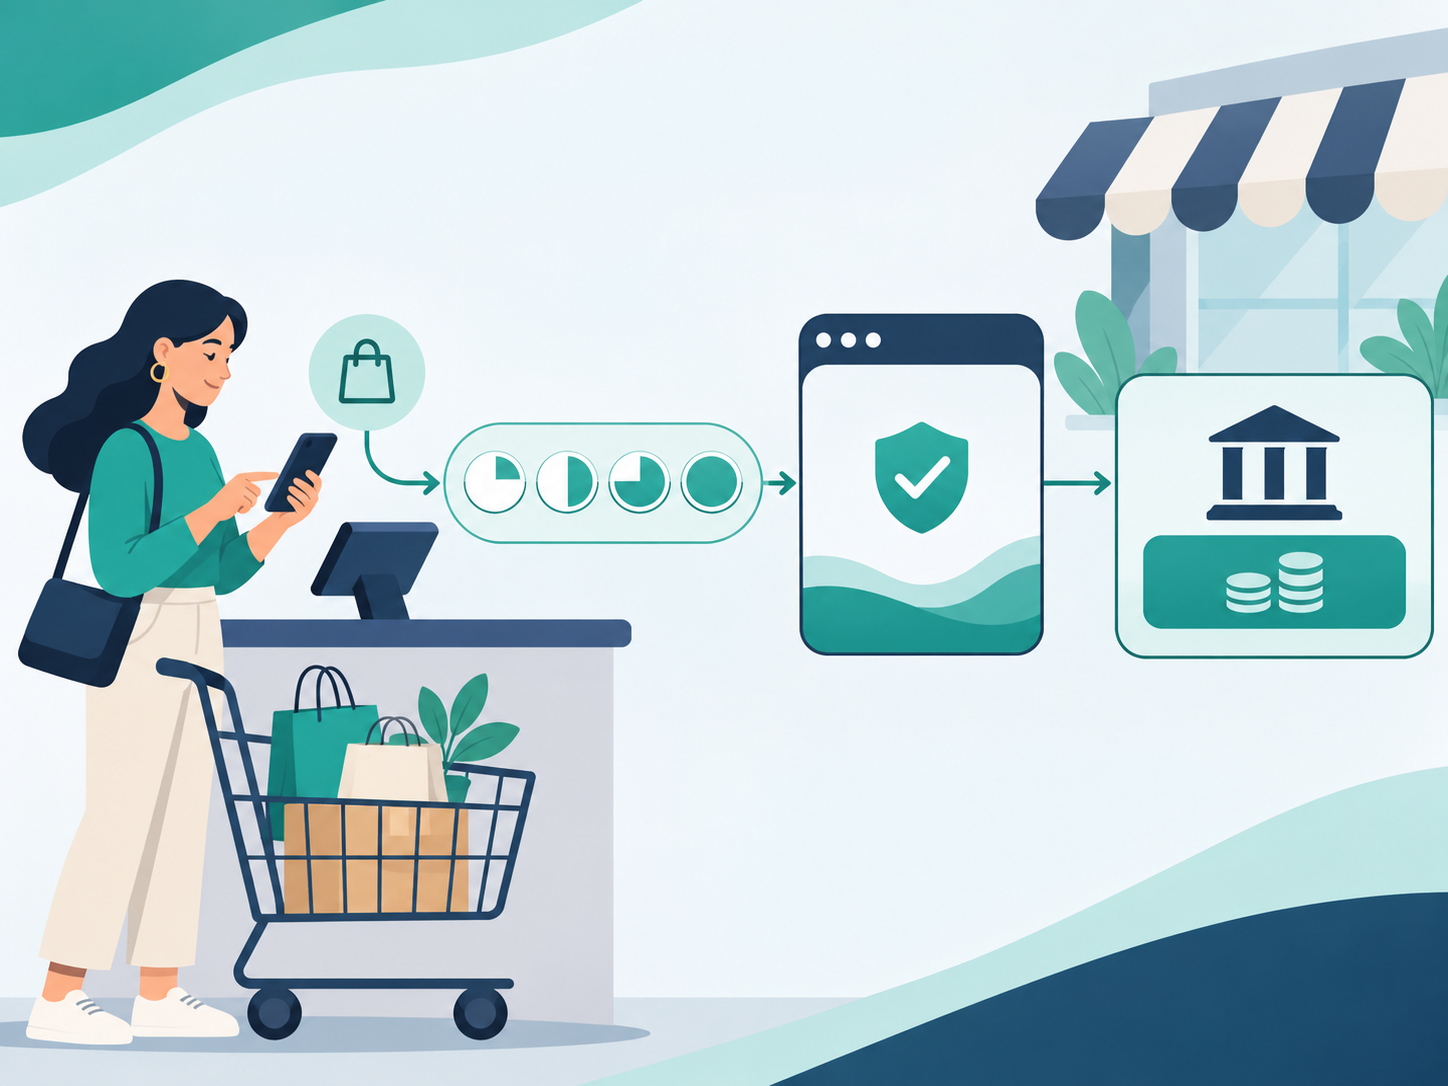
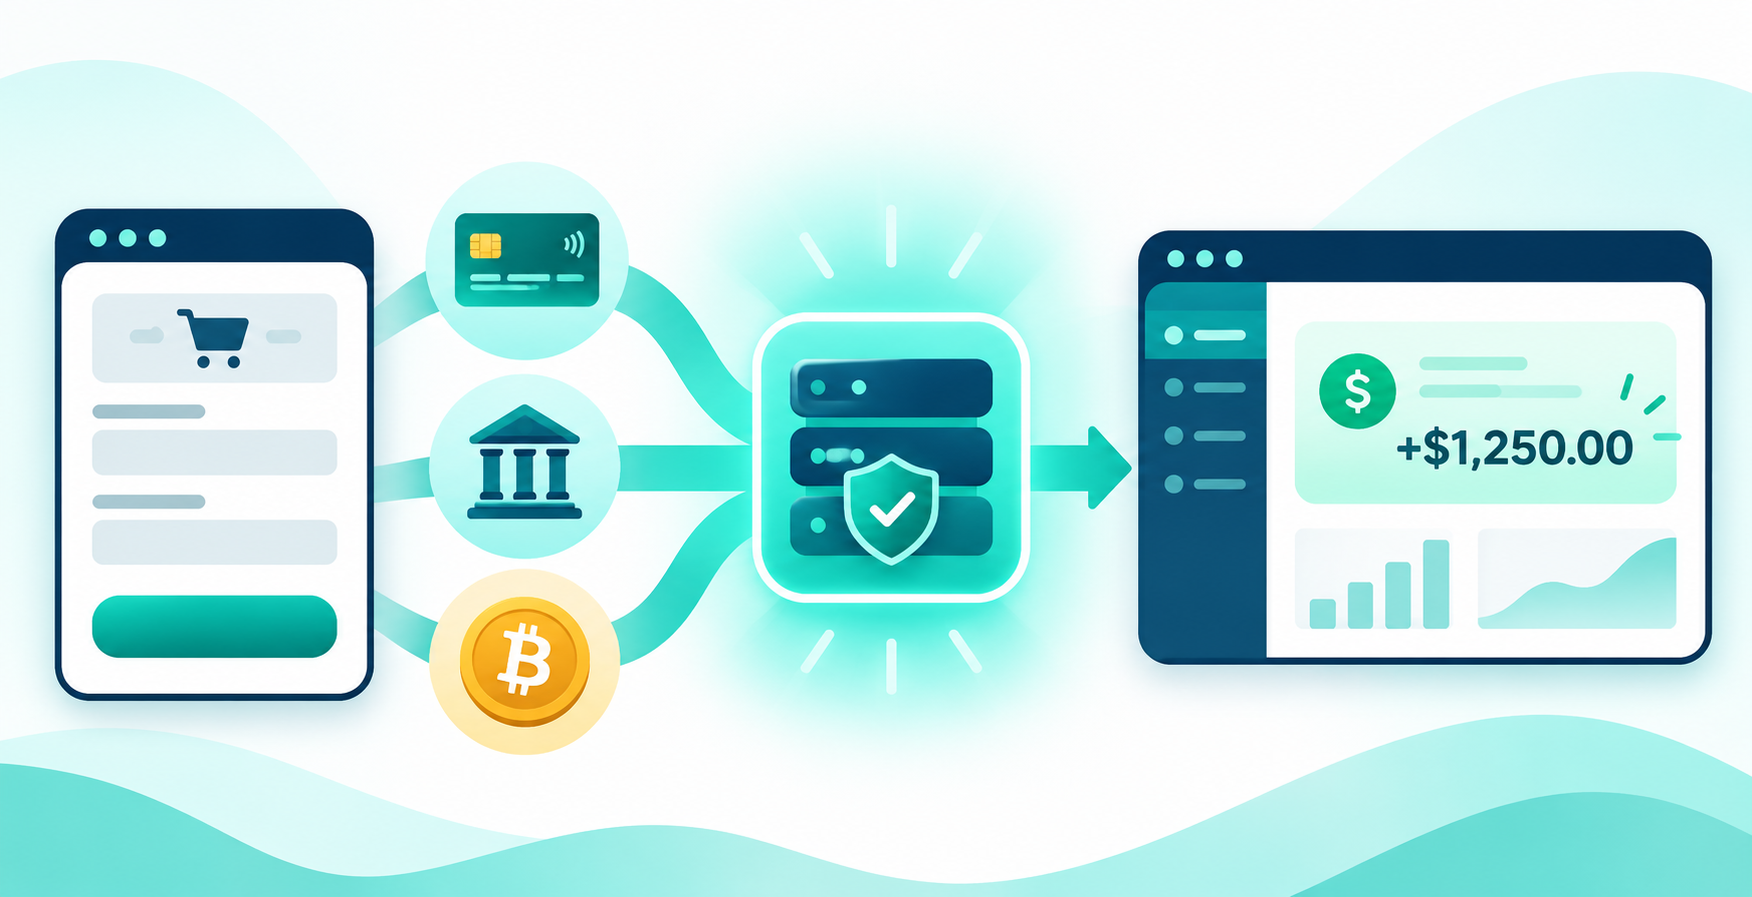
The money flow is simple:
- The customer chooses a BNPL option at checkout.
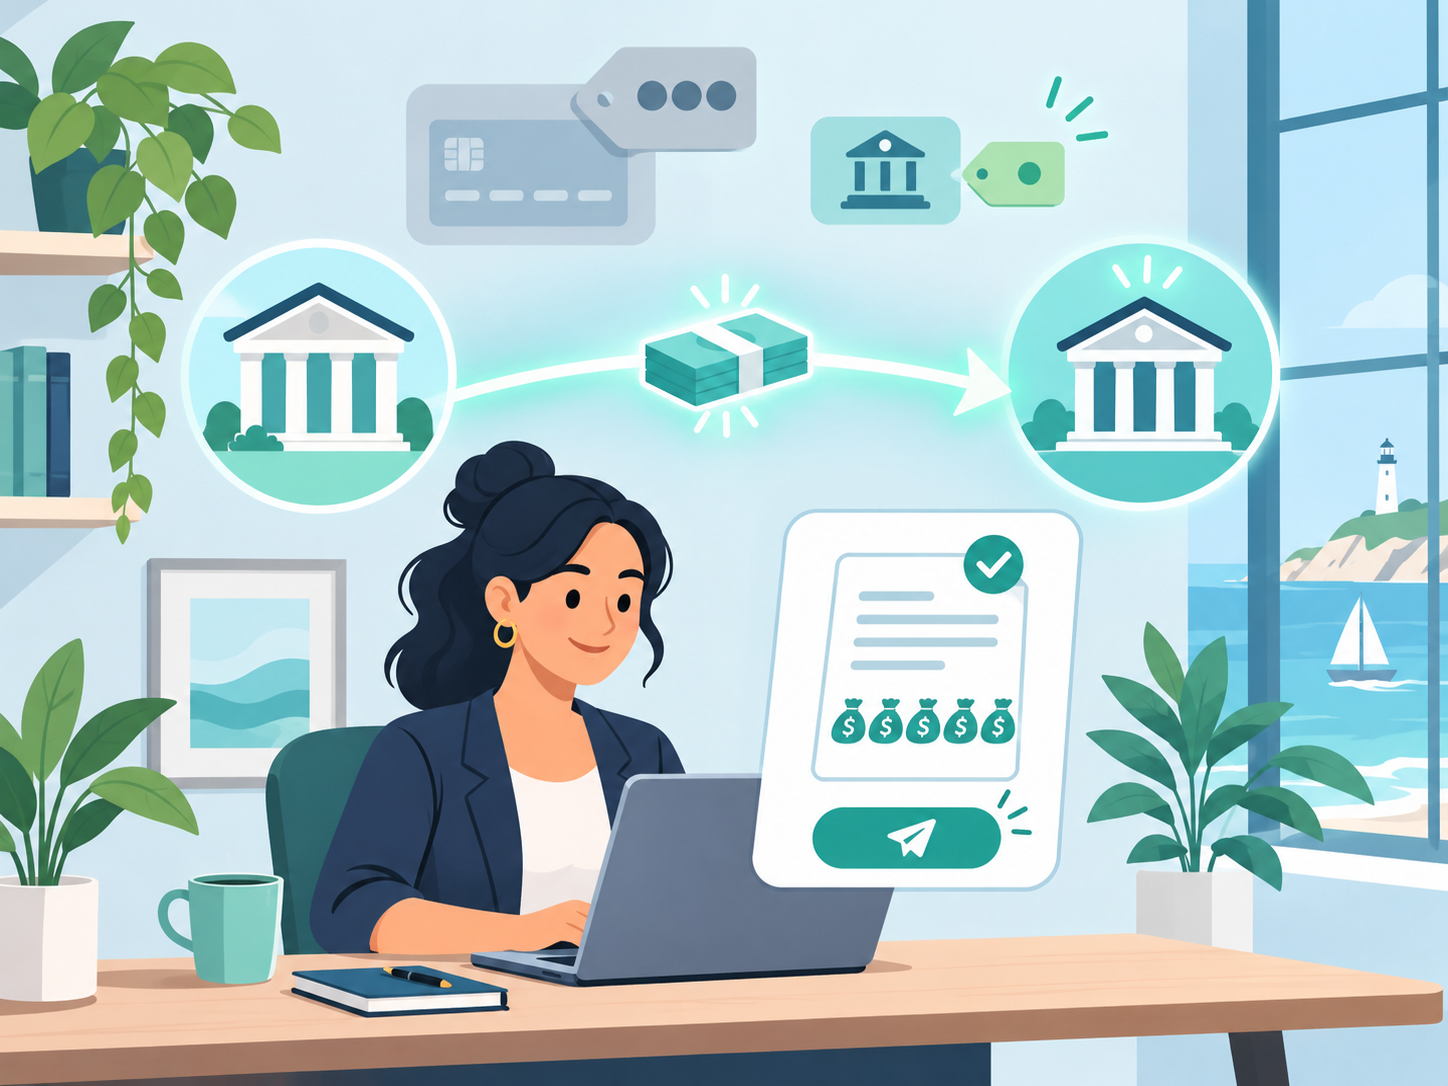
- The BNPL provider approves the purchase and pays the merchant up front, minus a fee.
- The customer repays the BNPL provider over time.
Customer
Afterpay, Klarna
or other BNPL
Coastal Pay
Gateway
Merchant bank
Most small and mid-size merchants access BNPL through a payment processor or gateway, not by opening a standalone Afterpay account. Approvals, refunds and disputes can also work a little differently from card payments, because the BNPL provider carries the customer credit decision. That is why the best choice is usually the platform with the cleanest BNPL integration for your setup, not just the lowest card rate.
Here’s what really matters when you pick a provider for Afterpay and BNPL
- BNPL brands supported: Afterpay, Klarna, Affirm, PayPal Pay Later and others.
- Fees and settlement: the BNPL fee, how it differs from your card rate, and when funds arrive.
- Integration fit: Shopify, WooCommerce, a custom site or an in-person POS each work differently.
- Customer experience: how clearly BNPL appears on product pages, cart and checkout, especially on mobile.
- Operations: reporting, refunds, partial refunds and how disputes are handled.
- Support: help configuring and troubleshooting, not only documentation.
Coastal Pay’s differentiators in this list: instant approvals, no gateway fee, 2,000+ integrations and flat-rate pricing options.
Which platforms make it easiest to turn on Afterpay and BNPL today?
- Stripe: Afterpay and other BNPL methods are generally available through an existing Stripe integration, which makes it a popular, flexible choice for custom sites, WooCommerce and platforms.
- Shopify Payments: Shop Pay Installments is built into Shopify for eligible U.S. merchants, and Afterpay and other BNPL options can be added through the Shopify ecosystem. Best if you already live on Shopify.
- Square: supports Afterpay for in-person and online payments, which suits brick-and-mortar sellers who want POS and BNPL together.
- Coastal Pay: instant approvals, with Afterpay, Klarna and other alternative payment methods through one gateway and no extra gateway fee. Best for businesses that use multiple systems or want to keep their current storefront and POS.
- PayPal: Pay Later is simple if you are already in the PayPal ecosystem, but it is a narrower BNPL lineup.
Aggregators like Stripe, Square and Shopify are often enough when your sales run through one platform. A more customizable setup like Coastal Pay makes sense when you sell across several systems, want consolidated reporting for cards, ACH, wallets and BNPL, or want pricing you can review with a specialist.
| Platform | Ease of setup | BNPL breadth | Best for |
|---|
| Stripe | Very easy | Wide | Custom sites, WooCommerce, platforms |
| Shopify Payments | Very easy on Shopify | Wide through Shopify | Shopify stores |
| Square | Very easy | Afterpay plus others | Retail and in-person |
| Coastal Pay | Instant approval, guided setup | Afterpay, Klarna and more | Multi-system and growing merchants |
| PayPal | Easy | Pay Later | PayPal-centered businesses |
Details for other providers reflect general public information at the time of writing and change often. Confirm current availability and terms.
How do Stripe, Shopify, Square, PayPal and Coastal Pay compare on cost and features?
BNPL almost always costs more than a standard card payment. Merchant fees for BNPL are commonly quoted in the range of roughly 5% to 8% per transaction, compared with about 2% to 3% for cards, though your actual rate depends on the provider and contract.
| Platform | BNPL options | Typical BNPL merchant fee | Card pricing | Gateway fee |
|---|
| Stripe | Afterpay, Affirm, Klarna and others | Confirm with provider | Standard published rate | None on standard plans |
| Shopify Payments | Shop Pay Installments, Afterpay and others | Confirm with provider | Depends on plan | Bundled |
| Square | Afterpay | Confirm with provider | Standard published rate | None |
| PayPal | Pay Later | Confirm with provider | Standard published rate | None |
| Coastal Pay | Afterpay, Klarna and more | Confirm during quote | Flat 2.5% + $0.15 | $0 |
Where Coastal Pay can help is the part you control: your card rate and your gateway. With a flat 2.5% + $0.15 and no gateway fee, routing BNPL plus cards through one system avoids stacking platform fees on top of BNPL costs. BNPL provider fees themselves are set by the BNPL program, so ask for the exact fee in your quote and model the margin impact before launch.
On integrations, Shopify offers a native stack, Square offers its POS, and Stripe offers strong APIs. Coastal Pay connects to 2,000+ software vendors plus API access, so you can keep your existing storefront or POS. On support, many aggregators lean on self-serve documentation, while Coastal Pay offers a direct phone line at 888-266-1715 and helpdesk tickets.
Here’s how Coastal Pay handles Afterpay, Klarna and Affirm with no gateway fees
Coastal Pay’s gateway supports alternative payment methods including Afterpay and Klarna alongside cards, ACH, Apple Pay, Google Pay, Venmo and more. There are no separate gateway charges for running them through one system. Affirm availability can depend on your account and setup, so ask about it when you request your quote.
- Instant boarding: most standard-risk businesses are approved in about two minutes, so you can start quickly.
- One dashboard: cards, ACH, wallets and BNPL show up in one place, which simplifies reconciliation and reporting.
- Your platform, your choice: 2,000+ integrations and API access mean you do not have to change your POS or e-commerce platform.
- Risk and security support: PCI guidance and chargeback help from the Coastal Pay team.
Statement review: send Coastal Pay a recent processing statement and a specialist will model your card costs and your BNPL margin side by side. Request a statement review
Example scenario (hypothetical, for illustration only): an online store sells $50,000 a month. If $10,000 of that goes through BNPL at a 6% fee, BNPL fees are $600. The remaining $40,000 on cards at 2.5% + $0.15 per transaction, with an $80 average order (500 orders), costs $1,000 plus $75, or $1,075. Knowing these two lines separately lets you decide whether BNPL lifts conversion and order value enough to justify its cost.
What’s the right BNPL setup for your online, in-store or omnichannel business?
Shopify-only store
Shopify Payments with Shop Pay Installments is the simplest start. Add Afterpay if customers ask for it. Consider Coastal Pay if you also sell elsewhere and want consolidated reporting.
Omnichannel retail
Square works well for a single ecosystem. If you run different systems online and in store, Coastal Pay can sit behind them as the processor and gateway without disrupting workflows.
B2B and high-ticket services
BNPL fees hurt more on large tickets. For high-ticket sales, review whether ACH or negotiated card pricing is the better main method, and use BNPL as an optional choice.
Subscriptions and SaaS
BNPL is usually a poor fit for recurring billing. Focus on cards, ACH and wallets, and offer BNPL only on one-time purchases.
Quick checklist
- Do you sell across more than one system or location?
- Is your average order value high enough that BNPL fees matter?
- Do you want cards, ACH, wallets and BNPL in one report?
- Do you want help with pricing and setup from a person?
If you answered yes to two or more, a Coastal Pay consultation is worth the call.
Here’s how to go live with BNPL through Coastal Pay in under a day
- Request a quote or demo. Have your monthly volume, average order value and a recent processor statement ready.
- Complete the instant application. Most standard-risk businesses are approved in about two minutes.
- Connect your software. Link your e-commerce platform, POS or custom checkout.
- Turn on BNPL. Ask for the BNPL methods you want and confirm eligibility and fees.
- Test and launch. Run test purchases, check refunds and settlement, and place BNPL messaging on product pages, cart and checkout.
The Coastal Pay team can help with integration, gateway configuration and button placement. After launch, review the dashboard to see how much of your checkout uses BNPL and whether average order value is moving.
Ready to add Afterpay and BNPL without extra gateway fees? Get Started or request a quote, and send a recent statement for a side-by-side savings analysis.
Frequently asked questions
Which merchant accounts are best for accepting Afterpay and other BNPL options?
Usually the platform with the cleanest BNPL integration for how you sell. Stripe, Shopify Payments, Square and PayPal are common. Coastal Pay suits businesses that want Afterpay, Klarna and more in one gateway with no gateway fee.
Do I need a separate Afterpay merchant account?
Usually not. Most merchants access BNPL through a processor or gateway.
Is BNPL more expensive than card processing?
Generally yes, often roughly 5% to 8% versus 2% to 3% for cards. Confirm current fees.
How quickly can I start with Coastal Pay?
Most standard-risk businesses are approved in about two minutes. Enabling BNPL methods and connecting your software may take more time.
Is Afterpay now called something else in the U.S.?
Yes, it is now branded Cash App Afterpay. Merchants generally see the same checkout and settlement process.