Frictionless Enterprise Checkout: 12 Changes You Can Ship This Quarter with Coastal Pay
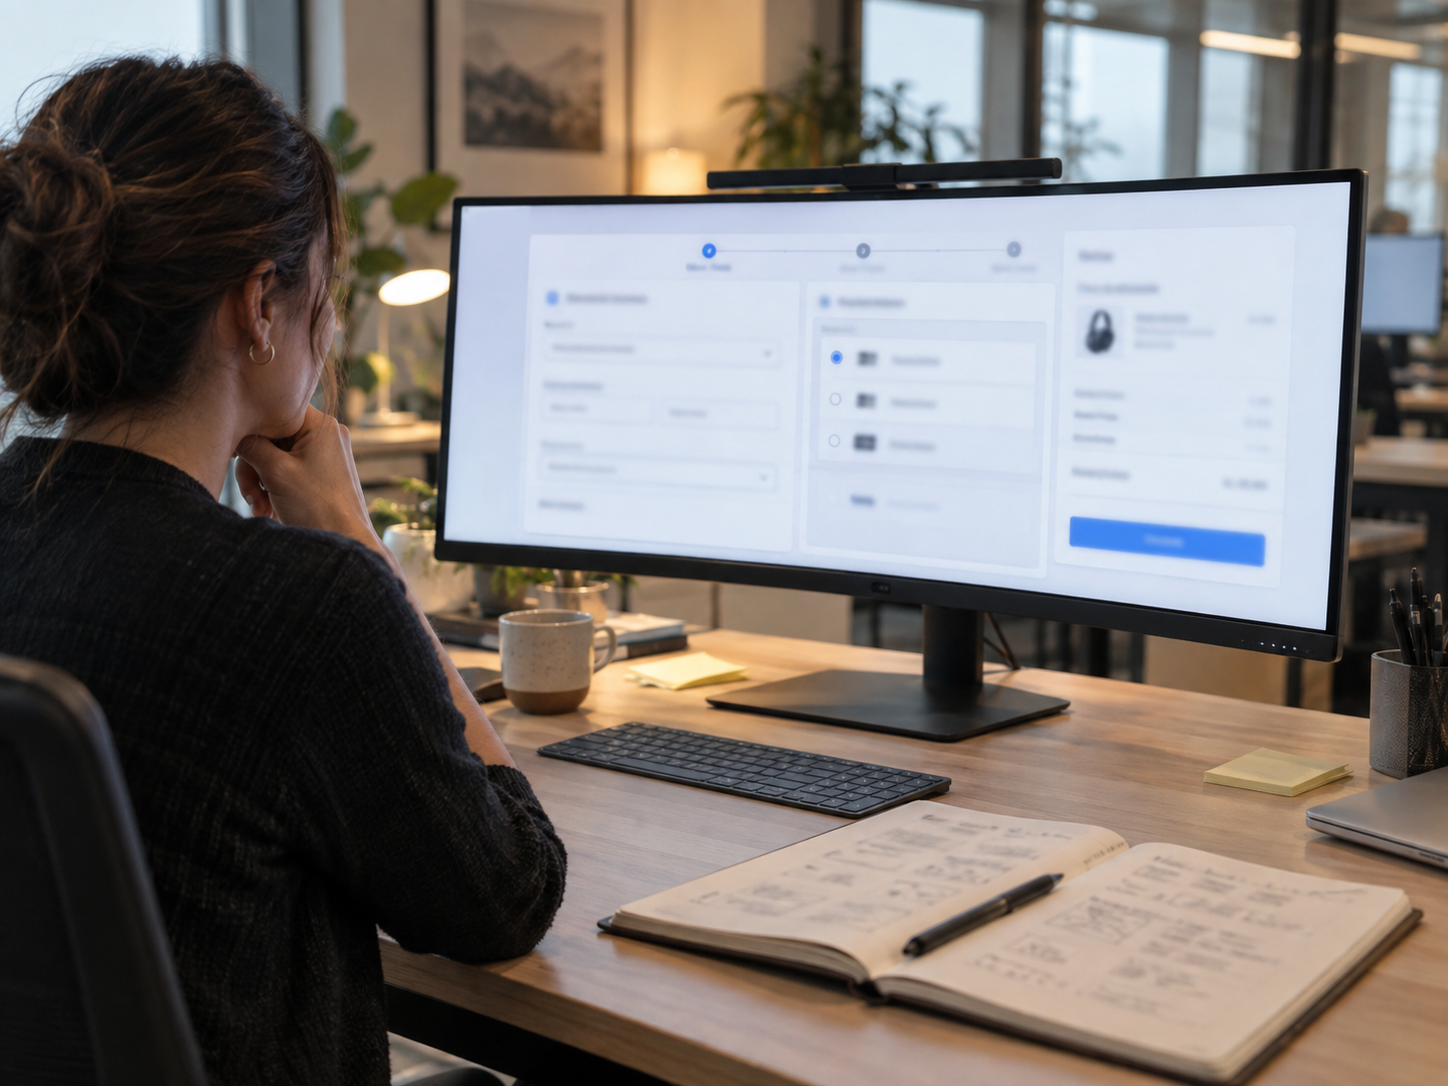
Enterprise buyers do not abandon checkout because it has too many steps - they abandon it because every step feels like work. In this guide, you will see 12 practical changes you can make right now to pre-fill data, hide procurement complexity, and turn your enterprise checkout into a fast, predictable flow powered by Coastal Pay. Each change is mapped to a specific Coastal Pay feature, so you have a direct path from reading to shipping.
Share
Let’s Define What “Frictionless” Really Means for Enterprise Checkout
Frictionless enterprise checkout is not about removing all fields. Procurement workflows, purchase orders, tax exemptions, and approval routing are legitimate requirements – removing them would break the buyer’s internal process, not make their experience better. Frictionless means minimizing buyer effort per dollar of order value by automating every data point the system already knows and only asking for data the system genuinely needs from the buyer in this session.
The North-Star Principle
Do not ask the buyer to tell you something your system already knows. Do not ask the buyer to make a decision your system can safely make for them.
What Makes Enterprise Checkout Different From Consumer Checkout
- Purchase orders: Many B2B buyers must reference a PO number to complete a purchase for internal approval. The PO field must exist – but it should only appear when the buyer’s payment method selection indicates they need it.
- Approval routing: Many enterprise orders above a threshold require manager approval before fulfillment. The checkout must communicate clearly whether the buyer is placing an order or submitting one for approval – and whether their card will be charged immediately or after approval.
- Tax exemptions: Many B2B buyers operate under tax exemption certificates. The checkout must support tax ID or certificate upload without making every buyer navigate a tax workflow that most of them do not need.
- Vaulted payment methods per entity: A large enterprise account may have multiple purchasing departments, each with their own corporate card. The checkout should present the buyer’s applicable vaulted options, not a global vault they must search through.
Coastal Pay’s enterprise payment infrastructure handles tokenization, vaulted profiles, and API integration across these dimensions. The changes in this guide map specific UX patterns to specific Coastal Pay capabilities.
Here’s Why Your Current Enterprise Checkout Is Slowing Deals Down
Before mapping the 12 fixes, diagnose the four most common failure patterns in B2B checkout flows:
Failure Pattern 1: Repeated Data Entry for Returning Buyers
A buyer who has placed 12 orders in the last year should not need to enter their company name, billing address, or shipping location on order 13. Every field a returning buyer must re-enter is a point where the buyer considers whether the purchase is worth the effort – and for large enterprise orders, that friction compounds at every required field. Business impact: Increased time-to-submit, increased support tickets asking “can you pre-fill my information,” and lower reorder rates compared to competitors with remembered-preference flows.
Failure Pattern 2: Forced Account Creation Mid-Checkout
Interrupting a buyer mid-checkout to require account registration adds a mandatory step that many enterprise buyers delegate to a purchasing assistant who does not have authority to create an account on behalf of the company. Business impact: Checkout abandonment specifically at the account creation gate, often followed by an offline workaround (email or phone order) that costs more to process than the online order would have.
Failure Pattern 3: Opaque Final Totals
Enterprise buyers and their approvers need confidence that the amount submitted for payment or approval is the full and final amount. Totals that change between the cart review screen and the payment confirmation screen, or that do not clearly show discounts, taxes, shipping, and fees, create approval-stage delays while the buyer’s finance team investigates the discrepancy. Business impact: Approval delays that convert to churned deals when the vendor offers net-30 and the approval takes 45 days to clear.
Failure Pattern 4: Brittle Error States on Complex Orders
A card decline that resets a 40-item purchase order forces the buyer to rebuild the entire cart to try an alternate payment method. This is catastrophic for enterprise orders and creates a category of buyers who refuse to use online checkout for large orders as a result. Business impact: Systematic avoidance of online checkout for high-value orders – the highest-margin order category – replaced by phone and email procurement that costs 5 to 10 times more to process operationally.
How Can You Recognize Enterprise Buyers and Pre-Fill Everything Safely?
Changes 1 and 2 of your 12-item roadmap: buyer recognition and auto-fill.
Change 1: Use Coastal Pay’s Vaulted Customer Profiles for Pre-Fill
Coastal Pay’s gateway supports customer profile creation that stores company name, legal entity, contact details, billing and shipping addresses, and vaulted payment method tokens against a customer ID. When a returning enterprise buyer authenticates – via SSO, account login, or session cookie – your checkout calls the Coastal Pay API to retrieve their profile and pre-populates all stored fields immediately.
The buyer lands on a checkout that shows:
Company:  Acme Corporation    [Edit]
Contact:  J. Smith             [Edit]
Ship to:  Acme HQ, 123 Main   [Change]
Bill to:  Same as ship         [Edit]
Payment:  Visa ....4821        [Change]
Every field is editable but none requires active input unless the buyer chooses to change it. The buyer’s path to order submission is a single review and click.
Change 2: Connect ERP and CRM Identity Via Coastal Pay’s Integration Layer
For enterprise buyers authenticated via SSO (Okta, Azure AD, Google Workspace), Coastal Pay’s 2,000+ software integrations and REST API allow your checkout to pull company, department, and contract pricing information from your ERP or CRM and present it in checkout without requiring the buyer to enter any of it. A buyer authenticated through Salesforce as Acme Corporation’s Account ID 00QXX1234 can have their contract pricing, tax status, and preferred shipping address surfaced at checkout automatically.
Key UX requirement: Every pre-filled field must have a visible, prominent Edit control. Pre-filling that cannot be corrected causes a different class of problems – buyers who cannot fix a wrong address will abandon rather than call support.
Here’s How to Hide Procurement Complexity Without Losing Control
Changes 3 and 4: progressive disclosure and conditional field logic.
Change 3: Use Progressive Disclosure for Procurement Fields
Purchase order fields, cost center codes, internal reference numbers, and tax exemption IDs should not appear in the checkout unless the buyer’s selection context requires them. The pattern:
Payment method:
  (•) Corporate Card [card pre-filled]
  ( ) Purchase Order  -- selecting this reveals: PO Number [input]
  ( ) Invoice / Net 30 -- selecting reveals: Terms confirmation
Only the chosen payment method’s required fields appear. A buyer paying by corporate card never sees the PO number field. A buyer paying by purchase order never sees the card entry component. Neither buyer needs to navigate complexity that does not apply to their transaction.
Change 4: Configure Conditional Fields via Coastal Pay’s API
Coastal Pay’s REST API allows your checkout to retrieve buyer-specific payment method options and contract configurations. When the buyer’s account ID indicates they are on a Net-30 contract, the checkout can present “Invoice” as their default option without the buyer needing to select it. When the account ID indicates tax exemption status, the tax field can be suppressed or pre-filled with the exemption certificate number from the profile. The buyer never sees fields that do not apply to their specific account configuration.
What Should a High-Converting Enterprise Checkout Layout Look Like?
Change 5: checkout layout redesign for returning enterprise buyers.
The 4-Section Linear Layout
For returning enterprise buyers where pre-fill is active, the checkout should collapse to four sections – each pre-populated and collapsible with a single edit control:
CHECKOUT

+--------------------------------------------------+
| 1. Customer                                      |
|    Acme Corporation                              |
|    J. Smith  |  jsmith@acme.com                 |
|    [Edit contact]                                |
+--------------------------------------------------+
| 2. Delivery                                      |
|    Acme HQ                                       |
|    123 Main St, New York, NY 10001              |
|    [Change address]                              |
+--------------------------------------------------+
| 3. Payment                                       |
|    (•) Corporate Visa  ....4821                 |
|    ( ) Purchase Order                            |
|    ( ) Invoice / Net 30                          |
+--------------------------------------------------+
| 4. Review                                        |
|    247 items                                     |
|    Contract discount           -$8,400           |
|    Shipping                        $0            |
|    Tax                         $3,820            |
|    TOTAL                      $43,620            |
|                                                  |
|          [Place Order]                           |
+--------------------------------------------------+
For a fully pre-filled returning buyer, this layout is a single-screen checkout. The buyer reviews four sections, confirms, and clicks. The time from checkout entry to order submission for this buyer should be under 60 seconds.
Typical vs. Coastal Pay-Optimized Enterprise Checkout
| Dimension | Typical Enterprise Checkout | Coastal Pay-Optimized Checkout |
|---|---|---|
| Data entry for returning buyer | All fields empty, full re-entry required | All known fields pre-filled, edit-only |
| Procurement fields (PO, cost center) | Always visible regardless of payment method | Shown only when relevant payment method selected |
| Payment method selection | Card entry form always visible | Vaulted card shown; alternate methods in radio group |
| Order total visibility | Final total shown only at last step | Sticky order summary visible at all steps |
| Account creation requirement | Mandatory before checkout proceeds | Guest checkout first; account creation post-purchase |
| Error recovery on card decline | Form resets; cart may clear | All data preserved; alternative payment offered inline |
Here’s How to Use Coastal Pay’s Tokenization to Cut Form Fill Time in Half
Changes 6 and 7: vaulted payment methods and alternative payment presentation.
Change 6: Vault Card and ACH Tokens Per Entity or Department
Coastal Pay tokenizes card and ACH payment details at the point of first entry and stores the resulting token against the customer profile. For enterprise accounts with multiple purchasing departments, tokens can be stored per department ID within the same customer profile. When a buyer from the Finance Department of Acme Corporation reaches checkout, only the Finance Department’s approved payment methods appear – not the Marketing Department’s corporate card or the Executive team’s Amex. Department-scoped vault tokens reduce both checkout friction (fewer irrelevant options to scroll past) and payment authorization errors (buyers selecting a card they are not authorized to use).
Change 7: Present Apple Pay, Google Pay, ACH, and Corporate Cards in One Unified Payment Component
Enterprise buyers have diverse payment method preferences: a buyer making a $200 incidental purchase may prefer Apple Pay; the same buyer’s team making a $50,000 procurement order will use a corporate card or PO. Coastal Pay’s gateway presents all enabled payment methods – Apple Pay, Google Pay, Venmo, PayPal, ACH, and all card types – through a single unified payment component. The component detects the buyer’s device and available wallets automatically and presents the most relevant options prominently, without requiring the merchant to build separate integrations for each method or manage separate payment agreements per method.
The API call to retrieve a customer’s vaulted payment methods looks like:
GET /v1/customers/{customer_id}/payment_methods
Authorization: Bearer {api_key}

Response:
{
  "payment_methods": [
    {
      "type": "card",
      "last4": "4821",
      "brand": "visa",
      "label": "Finance Dept Corporate Visa",
      "default": true
    },
    {
      "type": "ach",
      "account_last4": "9301",
      "label": "Acme Primary Checking"
    }
  ]
}
Your checkout renders the returned methods as radio options with descriptive labels. No card number entry required for returning buyers. The buyer selects their method and confirms.
Let’s Talk About Pricing Clarity, Taxes, and Fees for Large Orders
Change 8: full pricing transparency before the order submission CTA.
Change 8: Surface Every Cost Component Above the Order Button
Enterprise buyers and their approvers need to see every line of the order total before clicking Place Order. A total that changes between the review screen and the confirmation screen – or that omits taxes, shipping, contract discounts, or surcharges – creates approval-stage delays that convert to churned deals. The sticky order summary component should always show:
- Subtotal (line items only)
- Contract or volume discount (labeled clearly as a reduction)
- Shipping (labeled “Included” if zero)
- Tax (pre-calculated, labeled with the applied rate)
- Any payment surcharge or dual pricing differential (labeled transparently – “Card processing fee: $X” if applicable)
- Applied credits or prepayments
- FINAL AMOUNT – bold, large, unambiguous
Coastal Pay’s gateway can pass surcharge and dual pricing information through its API to populate the checkout’s cost breakdown transparently. For enterprise buyers on dual pricing programs, the checkout shows both the card price and the ACH or cash price clearly before payment method selection, so the buyer’s choice is informed before any amount is committed.
Here’s How to Handle Accounts, SSO, and Approvals Without Adding Friction
Changes 9 and 10: account creation, SSO, and approval routing.
Change 9: Move Account Creation to After the Purchase
Mandatory account creation before checkout is a reliable abandonment trigger for enterprise buyers whose purchasing agent is completing the order but does not have authority to create an account on behalf of the company. The correct pattern: complete checkout as a guest or authenticated SSO user, then offer account creation on the confirmation screen with the transactional context already established. The buyer has already successfully placed the order; the account creation offer is an invitation to make the next order easier, not a prerequisite for the current order.
Change 10: Make Approval-Required Orders Explicit
When an order requires manager approval before fulfillment or payment capture, the checkout must communicate this explicitly in the CTA and confirmation. The pattern:
This order requires approval from your manager.
Your card will not be charged until the order is approved.

         [Submit for Approval]

You will receive a confirmation email with the
approval request status and your order reference.
This is categorically clearer than a generic “Continue” or “Place Order” CTA that does not distinguish between immediate charge and approval-gated charge. Buyers who misunderstand whether their card is charged immediately generate support tickets; approval-gated orders that charge immediately generate chargebacks. Both cost more than the UX investment to label the action correctly. Coastal Pay’s API supports payment intent creation with manual capture, enabling the “submit for approval, capture after approval” pattern without custom payment infrastructure.
Let’s Make Errors, Declines, and Edge Cases Easy to Recover From
Changes 11: error handling and payment failure recovery.
Change 11: Preserve All Data on Every Error and Offer Specific Recovery Paths
A card decline that clears a 40-line purchase order is not a payment failure – it is a checkout-destroying event that most enterprise buyers will not repeat. The patterns that prevent this:
- Inline field validation: Validate each field immediately after the buyer leaves it, not at form submission. A tax ID format error caught inline is corrected in 5 seconds. The same error caught at submission, after a buyer has entered 15 fields, is a frustrating rebuild.
- Preserve all data through payment errors: When a card declines, all order details, shipping information, PO number, and item quantities must remain in the checkout state. Only the payment selection resets. The buyer sees their order intact and a clear prompt to select an alternate payment method.
- Specific decline messaging: Coastal Pay’s webhook and API response codes distinguish between insufficient funds, expired card, and issuer-declined transactions. Map these to user-facing messages that suggest a specific action: “Try a different card” for insufficient funds, “Update your card details” for expired cards, “Contact your card issuer” for issuer declines.
- ACH as automatic decline fallback: For enterprise orders where the buyer has an ACH payment method vaulted, present ACH as the immediate alternative when a card declines. ACH authorization failure rates are significantly lower than card authorization failure rates for large enterprise B2B payments. Coastal Pay’s unified payment component can surface ACH automatically when a card decline is detected via webhook.
How Do You Measure If Your Enterprise Checkout Is Truly Frictionless?
Change 12: metrics and measurement infrastructure.
Change 12: Instrument the Full Checkout Lifecycle and Segment by Buyer Type
A checkout that converts 95% of simple $200 card orders but consistently stalls on $50,000 PO submissions is not frictionless – it is frictionless for one buyer type and broken for another. The metrics that reveal enterprise-specific friction require segmentation by payment method, buyer type, and order size:
The 10 Metrics to Track
- Checkout completion rate by payment method: Separate rates for card, ACH, PO, and invoice to identify which payment paths have abandonment problems
- Median time from checkout entry to order submission: By returning vs. new buyer. A returning buyer spending more than 3 minutes in checkout has a pre-fill problem.
- Number of fields manually entered by returning buyers: Any field that more than 20% of returning buyers enter manually (when it could be pre-filled) is a pre-fill gap
- Validation errors per checkout session: High error rates for a specific field indicate a format or UX problem with that field
- Payment failure rate by method and order size: Card decline rates for orders above $10,000 vs. below $1,000
- Approval abandonment rate: Percentage of orders submitted for approval that are never approved or rejected (abandoned in the approval queue)
- Checkout-to-order rate for orders requiring approval: vs. orders that complete without approval. Large gaps indicate friction specific to the approval path.
- Post-checkout support contacts: Tickets about billing totals, unexpected charges, or “where is my order” that originate from checkout confusion
- Payment method mix vs. optimal mix: If ACH is dramatically cheaper but adoption is low, the checkout is not surfacing ACH effectively to buyers who could use it
- Revenue per checkout session by buyer segment: The north-star metric. If returning enterprise buyers generate lower revenue per session than new buyers, the returning buyer checkout experience is creating obstacles that are suppressing order size
Coastal Pay’s gateway reporting and webhook event stream provide the raw data for most of these metrics. For payment failure rate and method mix analysis, Coastal Pay’s API returns detailed response codes per transaction that map to the metrics above. Contact 888-266-1715 to discuss analytics integration with your existing BI or data warehouse.
Here’s How to Ship Your First 12 Changes This Quarter with Coastal Pay
Grouped into three 30-day sprints, the 12 changes sequence by implementation complexity and business impact:
Sprint 1 (Days 1-30): Pre-Fill and Recognition
- Change 1: Implement Coastal Pay customer profile retrieval API to pre-fill company, contact, and address data for returning buyers
- Change 2: Connect ERP or CRM identity via Coastal Pay’s integration layer to pull contract pricing and tax status at checkout
- Change 6: Vault card and ACH tokens per department or entity within the Coastal Pay customer profile
- Change 7: Deploy the unified Coastal Pay payment component presenting all enabled methods in one UI
Sprint 2 (Days 31-60): Layout, Complexity, and Pricing
- Change 3: Implement progressive disclosure for procurement fields (PO, cost center, tax exemption) triggered by payment method selection
- Change 4: Connect conditional field visibility to Coastal Pay API response for buyer account configuration
- Change 5: Redesign checkout to 4-section linear layout with collapsed, pre-filled sections for returning buyers
- Change 8: Implement sticky order summary with all cost components (subtotal, discount, tax, fees, FINAL AMOUNT) visible at all steps
Sprint 3 (Days 61-90): Accounts, Approvals, Errors, and Measurement
- Change 9: Move account creation to post-purchase confirmation flow; implement guest checkout as default for unauthenticated buyers
- Change 10: Implement explicit “Submit for Approval” vs. “Place Order” CTA pattern using Coastal Pay’s manual payment capture API
- Change 11: Implement all-data-preserved error handling with specific decline messaging from Coastal Pay response codes and ACH fallback on card decline
- Change 12: Instrument the 10 checkout metrics with segmentation by payment method, buyer type, and order size using Coastal Pay gateway webhooks and reporting
Your Next Step
Explore Coastal Pay’s enterprise payment solutions, gateway and API documentation, 2,000+ integrations, and all alternative payment methods to map these 12 changes to your specific checkout stack. Coastal Pay’s team at 888-266-1715 can walk through your current checkout architecture and identify which of these changes can be shipped fastest against your existing integration.
Restaurant Blog Template Guide: 5 Plug-and-Play Posts That Also Sell More Tables
If you have ever stared at a blank screen trying to write a blog post for your restaurant, this guide is for you. Below you will find five plug-and-play templates – plus a full sample post about payments – that you can copy, customize in minutes, and use to bring more guests through the door while quietly highlighting how simple it is to pay at your place. Each template is written to work for any restaurant, in any city, for any cuisine. Just swap the brackets and publish.
How to Accept Corporate Cards Without Massive Fees: A Practical Playbook With Coastal Pay
If most of your customers pay with corporate cards, it can feel like you are working for Visa, Mastercard, and your processor instead of for your own business. There is no way to make those cards free – but there are very specific levers you can pull to bring your effective rate down, shift some cost off your plate, and stop getting surprised by junk fees. This guide covers all of them, anchored to Coastal Pay’s flat 2.5% + $0.15 all-in rate as a concrete benchmark at every step.
Easiest Payment Processors to Migrate to in 2026
Switching payment processors feels more complicated than it needs to be. The fear of downtime, lost recurring billing customers, or a botched e-commerce integration keeps many businesses overpaying their current processor for years. In this guide, we break down the actual complexity of migrating to a new processor in 2026, which processors make migration easiest, and how to execute a zero-downtime migration to Coastal Pay using a parallel-run strategy that eliminates the risk of payment disruption entirely.

Buy a POS System With Automatic Dual Pricing | Coastal Pay
Dual pricing lets your store display a cash price and a card price simultaneously – so card-paying customers cover the processing fee while cash and ACH payers get a lower price. With Coastal Pay, dual pricing is automatic: configured at the gateway level and deployed to your POS terminal without manual price entry per transaction. Legal in all 50 states. Compliant signage included. Effective processing rate approaches near 0%.