Let’s define what’s really slowing down new-location payment approval
Adding a location sounds simple, but the payment setup usually runs through six steps:
- Application: business and owner details for the new site.
- KYC: identity and ownership verification.
- Underwriting: risk review of the business and its expected volume.
- Gateway setup: credentials and settings for online or integrated sales.
- Terminal provisioning: hardware ordered, programmed and shipped.
- Test transactions: proof that everything works before opening day.
The delays rarely come from one big step. They come from small ones: manual reviews, back-and-forth emails, missing documents and handoffs between the processor and the bank.
It also matters whether you are adding a new legal entity or a new branch under an existing business. Many legacy providers treat both the same way, so a second location of a business they already know still goes through a fresh application.
A useful exercise is to map your last opening. Write down the date you signed the lease, the date you applied for payments, the date you were approved, the date terminals arrived and the date the first real sale ran. Most operators find that the approval gap is the one step they could have shortened, because it depends on the provider’s process rather than on construction, hiring or shipping.
Here’s why most processors take days instead of minutes
The slowness is built into the traditional model.
- One-by-one boarding. Each merchant account is boarded separately, even when the owners, tax ID and documents are the same for every location.
- Manual underwriting queues. Many banks and large processors review applications in a queue with fixed windows, often 24 to 72 hours, so delay is baked in before anyone looks at your file.
- Extra verification at scale. Some providers, including online platforms, ask for more information as your volume or number of locations grows. That can slow an expansion that was moving fast.
The practical result is that a store can be built, stocked and staffed while the payment line item is still marked pending. Timelines vary by provider and by business, so use these as typical patterns, not guarantees.
How does instant onboarding for new locations actually work?
Instant onboarding replaces the slow, manual parts with automated checks that run while you apply.
- Collect once, reuse intelligently. Business and owner information is gathered up front and reused where permitted, so a new location does not start from zero.
- Automated KYC and risk checks. Identity, business and risk checks run in real time instead of in an overnight batch.
- Bank validation. Deposit account details are checked during the application.
- Gateway provisioning. Credentials are issued as soon as the account is approved.
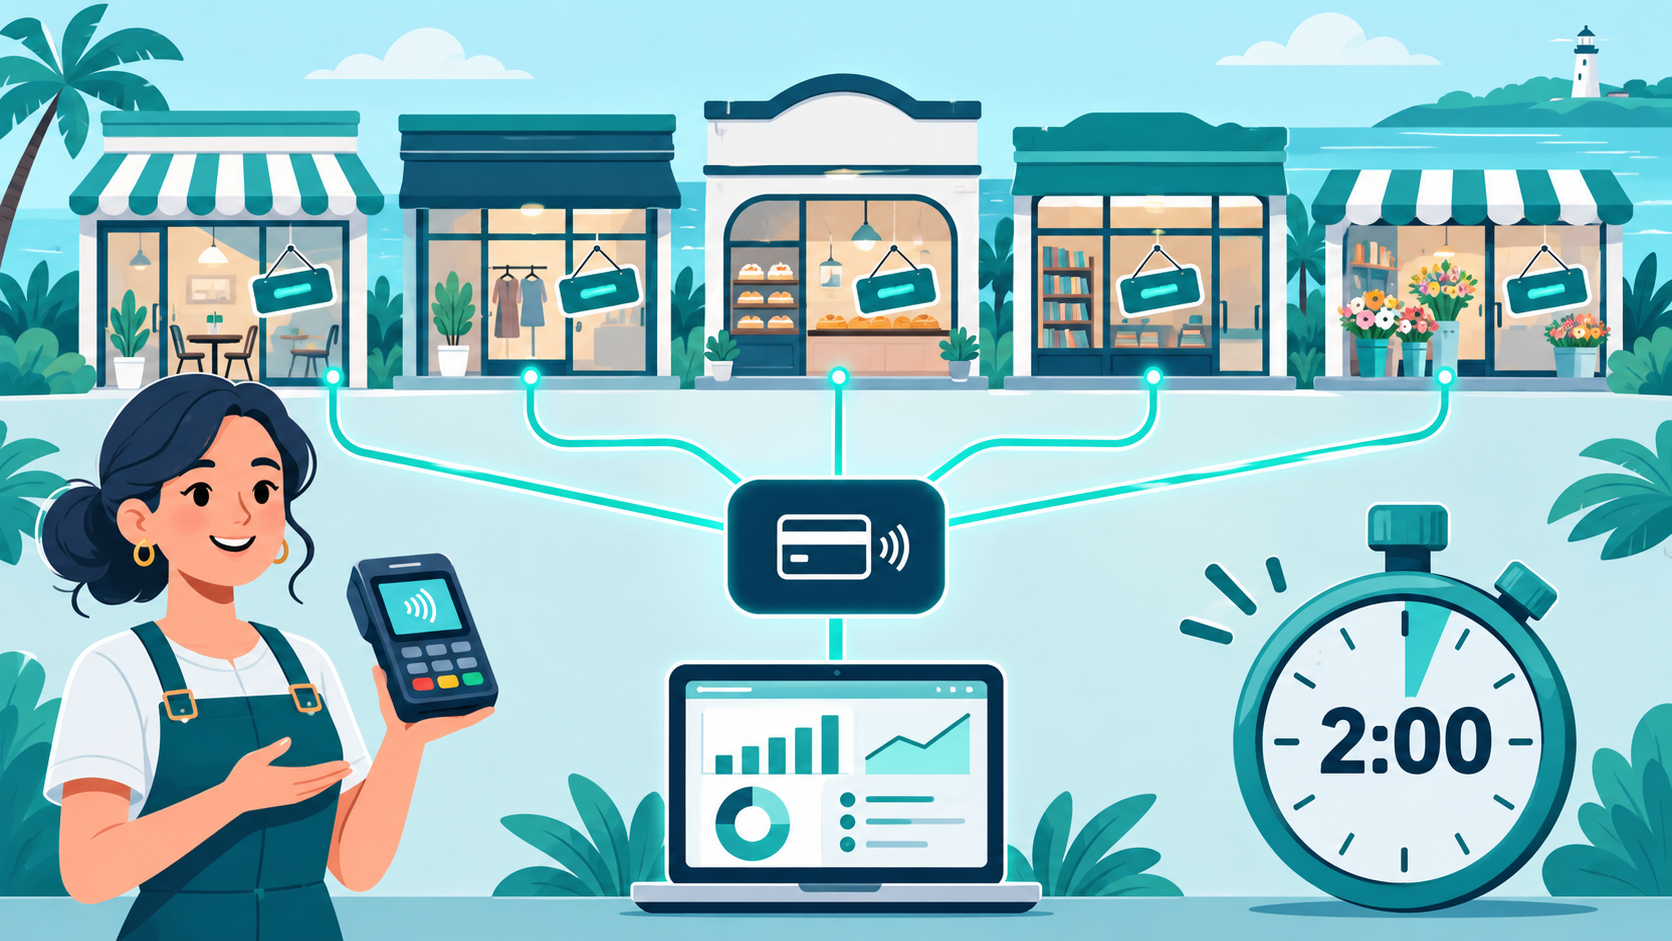
Compliance is still met. The difference is that the checks are automated for standard-risk businesses, which is why Coastal Pay can approve most of them in about two minutes. Unusual, high-risk or complex structures may still need manual review, and no provider can honestly promise instant approval for every location.
How the locations are structured matters. Several branches under one legal business are the simplest case. Separate LLCs under a parent company and independently owned franchises can need extra documents. Coastal Pay’s team can recommend the right account structure for yours.
What to ask any provider about instant approval
- What share of applications are approved instantly, and what triggers a manual review?
- Is each location a separate application, or can data be reused from the parent business?
- How long do hardware shipping and test transactions take after approval?
- Who do I call if an application is held up on a Friday before an opening?
What can you get done in 2 minutes with Coastal Pay?
- Enter business and owner info. Basic details, your EIN and owner information.
- Add your bank account. A bank account or voided check for deposits.
- Choose your hardware or software. Terminal, POS or online checkout.
- Submit. Most standard-risk businesses get an instant decision in about two minutes.
When you are approved, you can start taking payments in minutes, including cards, ACH and alternative methods such as Apple Pay and Google Pay, through the Coastal Pay Gateway. Hardware shipping and POS setup depend on your equipment, so plan for those separately.
Multi-location teams can repeat the same flow for each new store or office. Ask your specialist how much information can be reused from your parent business profile.
Ready to try it? Start Your 2-Minute Approval
How does Coastal Pay compare to Stripe, Square, and banks on approval speed?
The comparison below shows typical patterns. Actual timelines depend on your business, documents and risk profile, so confirm current terms with each provider.
New-location payment approval speed: Coastal Pay, Stripe, Square and banks| Factor | Coastal Pay | Stripe | Square | Typical bank |
|---|
| Time to approval | About 2 minutes for most standard-risk businesses | Often fast for a single small merchant | Often fast for a single small merchant | Often days, and varies |
| Time to first transaction | Minutes after approval, plus any hardware setup | Fast online; hardware varies | Fast with Square hardware | Depends on terminal and setup |
| Multi-location setup effort | One platform, one dashboard, same flow per location | Can require extra verification at scale | Can require extra verification at scale | Often a new application per location |
| Gateway provisioning | Issued on approval | Self-serve | Within Square’s ecosystem | Often a separate step |
Stripe and Square can be quick for one small merchant. They often slow down with volume reviews and added verification for larger or higher-risk setups. Coastal Pay’s advantage is repeatable speed across many locations, plus a team you can call when an application needs attention.
Here’s how multi-location and franchise teams keep every store moving
- One dashboard. A parent company can review sales, payouts and chargebacks across locations, while each site can still be reviewed on its own.
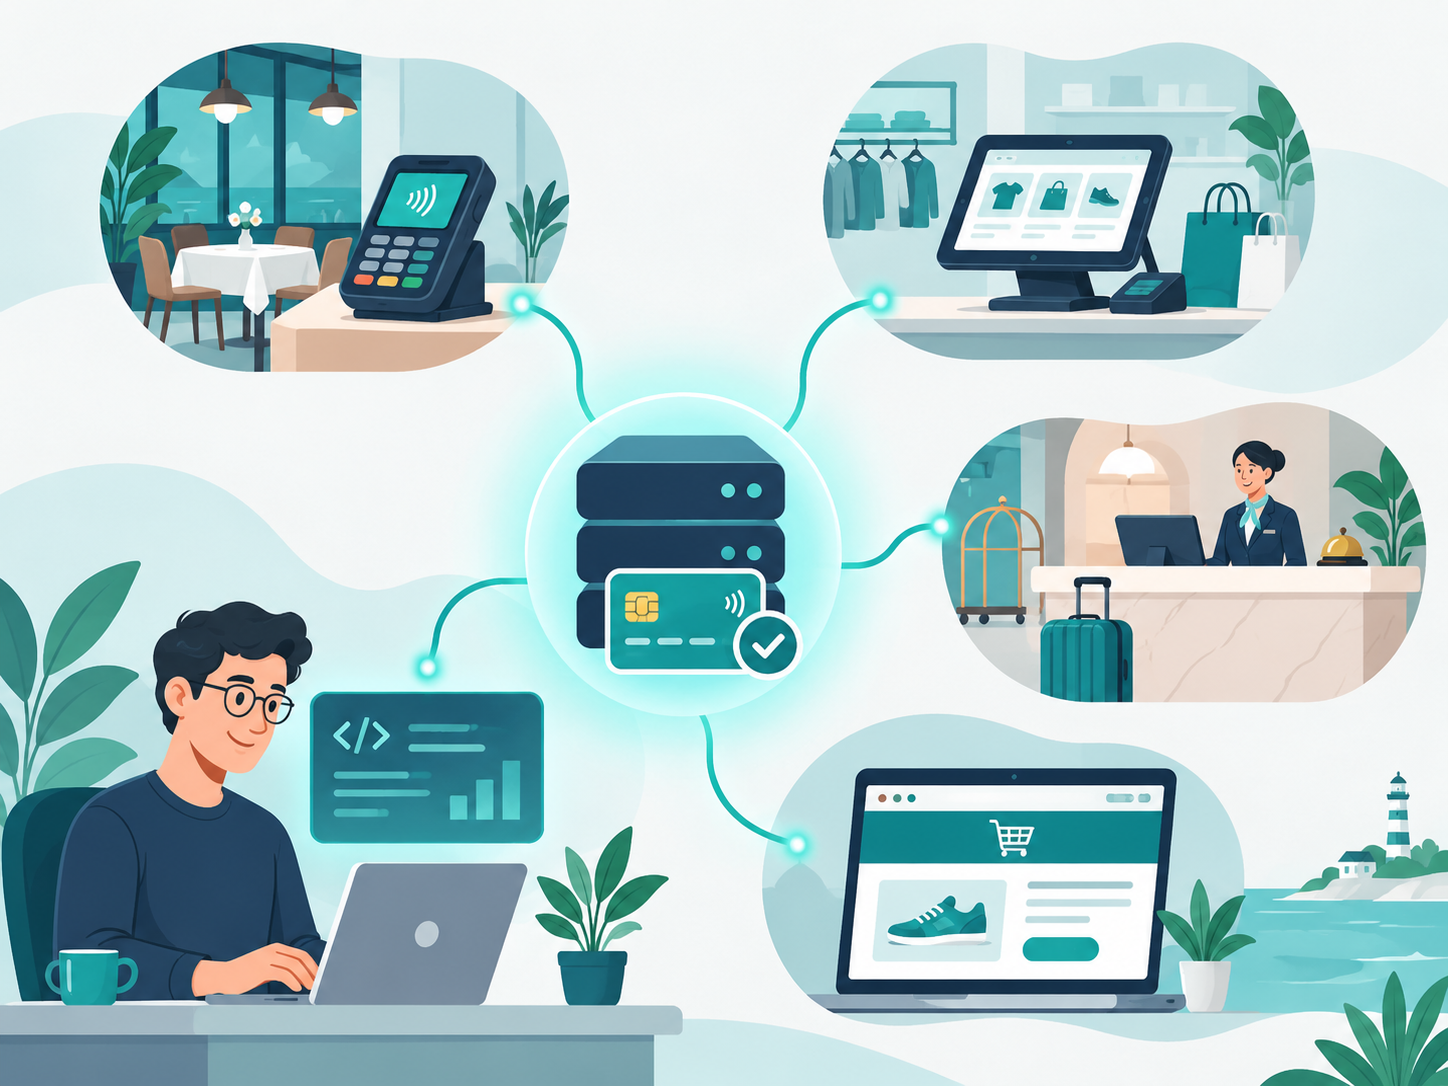
- 2,000+ integrations. Coastal Pay connects with POS, e-commerce and business software across retail chains, restaurants, hotels and auto dealers, so a new store can plug into systems you already use.
- Automation through the API. Teams can ask about connecting new-location setup to their internal systems, so opening a store in your system can trigger payment setup. Confirm the available options with the team.
For franchises, the main questions are who owns each location and how funds should be deposited. Raise both early so your Coastal Pay specialist can recommend a structure that fits.
Plan for the whole timeline, not just the approval. Payment approval is one dependency among many, alongside permits, hiring, inventory and signage. The goal is to make payments the one item that is never the reason an opening slips. When approval takes minutes, you can schedule hardware, staff training and a soft launch with confidence, instead of padding your calendar for a result you cannot control.
What results can you expect in your first 30 days?
Results depend on how many locations you open and how your current provider performs, so measure your own numbers. Here is a simple, hypothetical illustration, not a real customer.
Hypothetical example: A chain opens 10 locations in a quarter. If each one waits an average of 4 days for payment approval, that is 40 location-days of delay. If each store could otherwise bring in $1,500 per day at launch, that is up to $60,000 in sales at risk or pushed back. Switching to minutes for approval removes that waiting time, although hardware and staff training still take time.
Practical wins to look for:
- Opening weekend revenue is not held back by a pending approval.
- Less manual chasing of paperwork.
- Cleaner rollout plans for chains and franchises.
Track these KPIs after you switch: time from lease signing to first payment, number of locations activated per week, and the number of go-live dates missed because of payment delays.
Next steps: Turn days of waiting into minutes of setup
Have these ready before you click Get Started:
- Basic business details
- Your EIN
- Owner information
- A bank account or voided check
Then start the 2-minute approval and get your next location taking payments today. If your structure is more complex, such as franchises, multiple LLCs or high-volume B2B, contact the Coastal Pay team and they will help you plan it.
Quick answers
Is there a faster way to get payments approved for new locations?
Yes. Instant boarding and a centralized account structure can cut approval from days to minutes. Coastal Pay approves most standard-risk businesses in about two minutes. Underwriting and compliance checks still apply.
What do I need ready before I apply?
Basic business details, EIN, owner information and a bank account or voided check. Complex structures may need more documents.
Can Coastal Pay handle franchises or multiple LLCs?
The team can support complex structures such as franchises, multiple LLCs and high-volume B2B accounts. Contact them to plan the right structure.
Does instant approval mean no underwriting?
No. Identity verification, risk checks and compliance still happen. Instant boarding means they are automated for standard-risk businesses, while higher-risk accounts may need manual review.
Can new locations be onboarded automatically?
Coastal Pay offers API access. Ask the team about connecting new-location setup to your internal systems.
Ready to turn days of waiting into minutes? Start Your 2-Minute Approval or call 888-266-1715.